The global humidifier market is at a critical industry turning point. According to statistics from multiple market research firms, by 2025, the global market size for household air humidifiers will reach approximately $6.8 billion, while the commercial and office sector will account for about $3.1 billion, and the industrial sector will total approximately $16 billion. Behind these three figures lie three distinctly different growth logics, technological pathways, and competitive ecosystems. What is even more noteworthy is that humidifiers are breaking free from their consumer label as “luxury small appliances” and rapidly evolving into an industrial role as “industrial infrastructure”—a transformation that opens up a trillion-yuan-level potential far exceeding the $3.8 billion household market.
I. The Household Market: A Health Awareness Awakening and the Smart Technology Wave
The global household humidifier market is projected to reach approximately $6.8 billion in 2025 and is expected to grow to $9.2 billion by 2032, with a compound annual growth rate (CAGR) of about 5.2%. The growth logic of this market is rooted in consumers’ heightened awareness of indoor air quality.
From a technological perspective, the residential market is dominated by ultrasonic humidification technology. Ultrasonic humidifiers use high-frequency vibrations—2 million times per second—to atomize water into ultrafine particles ranging from 1 to 5 micrometers, offering advantages such as quiet operation, energy efficiency, and high humidification intensity. These products feature relatively simple designs and controllable costs, making them suitable for large-scale mass production and channel distribution.
In terms of the competitive landscape, the residential humidifier market features numerous participants and relatively low industry concentration. International brands such as Panasonic, Philips, Honeywell, and Dyson compete alongside traditional home appliance giants and emerging smart hardware brands. Online channels have become the primary battleground, where leading brands hold an advantage due to their traffic resources and brand recognition; however, new brands still have opportunities to enter the market through niche positioning.
II. Commercial and Office Market: Driven by Building Health and Compliance
The humidifier market in the commercial and office sector is valued at approximately $3.1 billion and is projected to grow to $6.5 billion by 2035, with a compound annual growth rate (CAGR) of about 7.5%. The growth rate of this market has already surpassed that of the residential market, reflecting the rapid emergence of a critical demand for humidity control in commercial settings.
The growth dynamics of the commercial office market differ fundamentally from those of the residential market. In commercial settings such as office buildings, hospitals, schools, and data centers, humidifiers are no longer “optional” but rather an integral part of building environmental management systems. Key drivers include: increased awareness of the impact of indoor air quality on employee health and productivity; new demand driven by the expansion of commercial real estate; mandatory regulations on building air quality in various countries; and complementary purchases resulting from HVAC system upgrades.
North America dominates the commercial humidifier market with a share of approximately 38%, a trend closely linked to its strict building air quality regulations and mature building management systems. The Asia-Pacific region, driven by rapid urbanization and industrialization, has become the fastest-growing regional market.
III. Industrial Market: The “Invisible Infrastructure” of Precision Manufacturing
The industrial humidifier market is projected to reach approximately $16 billion by 2025, marking sustained growth from $11.5 billion in 2016. Not only is this the largest of the three market segments, but it also boasts the most robust growth logic—industrial humidifiers are no longer merely “environmental control equipment,” but rather “industrial infrastructure” directly tied to product yield, production efficiency, and compliance costs.
Demand growth in the industrial market stems primarily from the manufacturing sector’s transition toward greater precision and sustainability. In electronic chip manufacturing, humidity fluctuations directly impact product yield; in pharmaceutical production, GMP compliance requirements drive a rigid demand for high-precision humidification equipment that prevents secondary contamination; and in lithium-ion battery production, the electrolyte filling process requires an ultra-low-humidity environment with a relative humidity below 1%. The explosive growth of the new energy industry (lithium-ion batteries, photovoltaics, and hydrogen energy) is opening up entirely new growth opportunities for industrial humidifiers. Additionally, the global boom in data center construction has created a strong demand for precise humidity control—the market for data center humidifiers is projected to grow from $1.34 billion in 2025 to $2.78 billion in 2035.
IV. The Path to Transformation: From “Small Appliances” to “Major Infrastructure”
The transformation of humidifiers from “lifestyle-enhancing small appliances” to “industrial infrastructure” is not merely a matter of market expansion, but a profound transformation involving product definition, technological systems, business models, and the industrial ecosystem.
Elevating the Product Definition. The core value of household humidifiers lies in “enhancing comfort,” with design priorities focused on aesthetics, quiet operation, and portability. In contrast, the core value of industrial humidifiers lies in “ensuring production,” with design priorities centered on precision, reliability, and continuous operation. China’s national standards system has clearly distinguished between household humidifiers and industrial-grade humidifiers—the GB/T 23332 series of standards applies to humidifiers for household and similar uses, while industrial-grade equipment falls outside its scope. This distinction at the standards level precisely confirms the fundamental differences in product definition between the two.
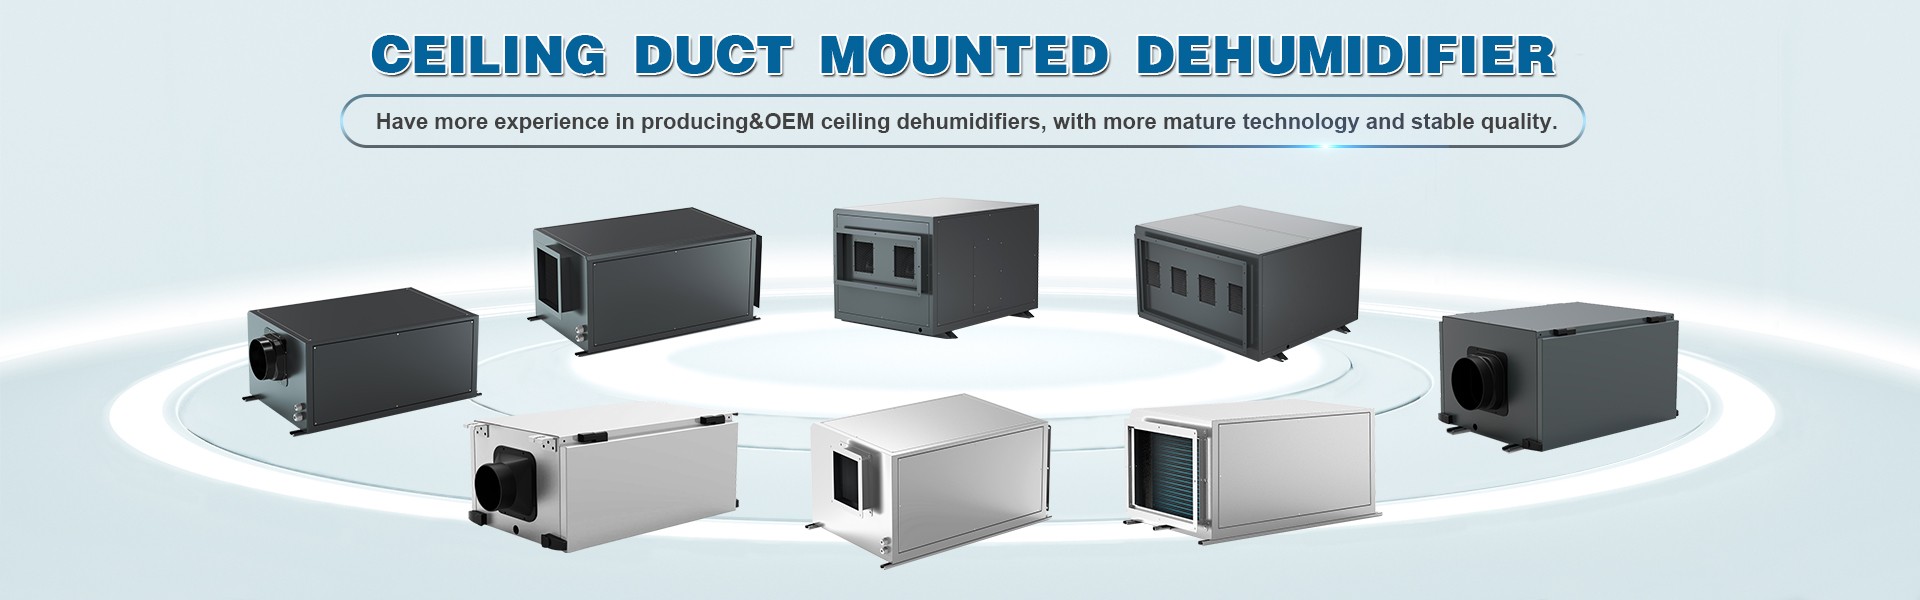
Technological Evolution. Household humidifiers primarily rely on ultrasonic atomization technology, featuring simple structures and controllable costs. Industrial humidification, however, involves multiple technical approaches, including isenthalpic humidification, isothermal humidification, and air-water mixing. More importantly, industrial settings require deep integration of equipment with building management systems and manufacturing execution systems. The transition from a “standalone device” to a “system component” results in an exponential increase in technical complexity.
Evolution of Business Models. The residential market is dominated by B2C retail, with competition centered on brand, distribution channels, and price. The industrial market, on the other hand, is primarily driven by B2B project-based sales, where competition revolves around system integration capabilities, full lifecycle services, and customized solutions. The sale of equipment is merely the starting point for service; subsequent operations and maintenance, upgrades, and data services constitute longer-term revenue streams.
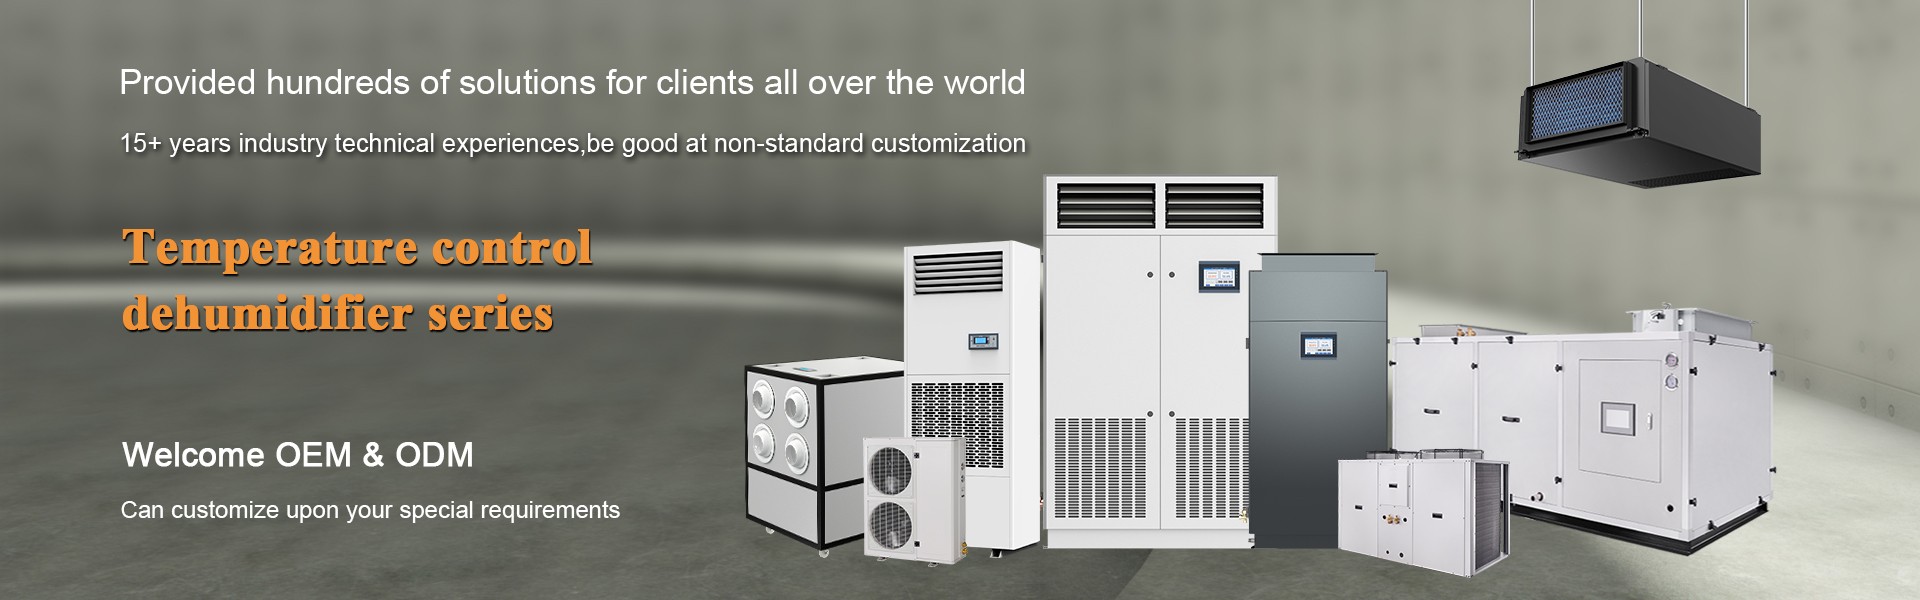
Restructuring of the Industrial Ecosystem. In the industrial sector, humidifiers are becoming part of a broader industrial landscape—integrating with HVAC systems, linking with building automation systems, and interfacing with industrial internet platforms. Emerging applications such as data centers, semiconductor wafer fabs, and new energy battery factories are elevating humidifiers from peripheral devices to core infrastructure.
Conclusion
A $3.8 billion residential market, a $3.1 billion commercial market, and a $16 billion industrial market—these three figures trace a value transition curve from the consumer end to the industrial end. The residential market serves as the foundation, providing the basis for technological validation and economies of scale; the commercial market acts as a bridge, elevating humidification from “improvement” to “management”; and the industrial market represents the ceiling, elevating humidification from a “function” to “infrastructure.”
The underlying driving force behind this transformation lies in a fundamental shift in society’s perception of the value of “humidity control”—it is no longer merely a household item to combat winter dryness, but rather an industrial cornerstone that safeguards precision manufacturing, protects data security, and supports green energy. As humidifiers move from living rooms into cleanrooms and from bedrooms into data centers, the industrial potential they embody has only just begun.
 vivienhu0427@hotmail.com
 +86 15958041362
 vivien@hzfreeair.com
